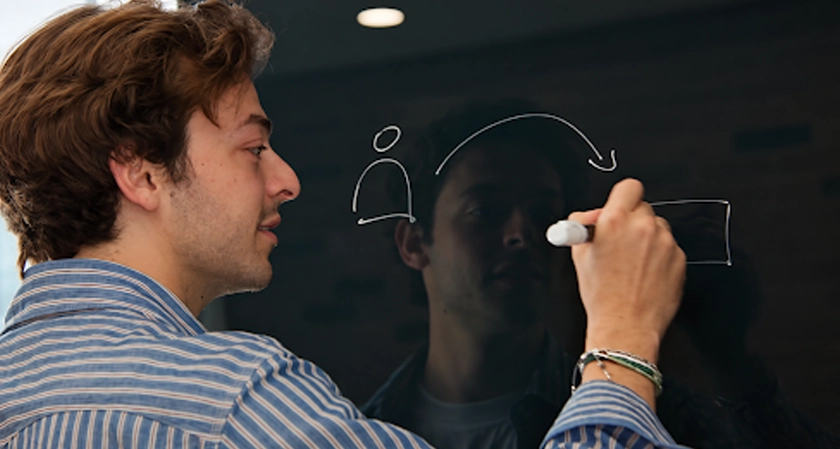
Full automation is often the most appealing narrative in financial compliance. It promises fewer manual reviews and quicker decisions, with software managing cases from intake to outcome with minimal human intervention. This perspective assumes that expert judgment primarily contributes to delays.
In contrast, Alexandre Berkovic takes a different approach. His systems are designed to handle repetitive evidence work, allowing people to focus on decisions with significant consequences. He clearly articulates the operating reality.
"Compliance teams inside banks and fintechs spend the majority of their time on repetitive, high-volume verification tasks," says Alexandre Berkovic, who builds machine learning that clears the repetitive compliance grind.
A specialist in designing multi-agent systems for financial-crime work that leave an audit trail, he can get the model running inside banks without a heavy rebuild.
He adds: "Sanctions screening, document authenticity checks, identity resolution, and open-source research. The list goes on. These tasks are statistically noisy, labor-intensive, and scale only by adding headcount. I wanted to make things easier, and the systems better."
Berkovic's objective was to make expert judgment available when a case actually demanded it. He wanted machine intelligence to be an infrastructure around the analyst, not a substitute for the analyst.
He reasoned that compliance work includes a large, repetitive layer that can consume attention. While this can eat up time, it does not necessarily require the full expertise of a trained investigator.
Berkovic argued that analysts must move among different areas, including screening tools, identity records, corporate documents, and transaction information. But all of this takes time as they assemble material and evidence to understand a case. That work matters, but much of the mechanics could be structured.
His new approach was to turn noisy case material into a score an analyst could act on: "I wanted to create a data science system that absorbed the repetitive layer."
This is how he developed his proprietary Interpretable Agentic Framework, a multi-agent architecture that structures evidence work so trained people can spend more time on interpretation, escalation, and decisions.
The system extracts structured signals by fusing multi-source evidence and generating calibrated risk scores: "Then human analysts can concentrate on the residual cases that genuinely require judgment," says Berkovic.
The Interpretable Agentic Framework is at the core of Sphinx, Berkovic's company, which has brought his approach into regulated financial institutions. Its system organizes evidence, combines signals from multiple sources, and produces risk scores that help prioritize cases.
Human analysts still retain the cases where uncertainty, unusual circumstances, or the consequences of a decision make contextual judgment important. High-risk outcomes and edge cases also stay subject to human review, particularly where a decision can contribute to a regulatory report or otherwise carry serious consequences.
Berkovic explains the target is to remove low-value friction so trained people can spend more time on interpretation, escalation, and decisions.
It can also help supervised institutions that face exacting regulatory expectations, where both missed risks and excessive false positives carry real consequences.
Berkovic says this is of particular importance in the United States, where regulatory expectations are exacting, and the cost of both false positives and false negatives is high: "This division of labor is especially powerful.
"It lets institutions handle more customers and transactions without hiring compliance staff at the same rate. The decisions that go to U.S. regulators and partner banks also stay more consistent and easier to audit."
Berkovic's background is not a typical corporate path. Before Sphinx, he worked on applied data science problems at Amazon, Schneider Electric, and Bear Robotics.
He holds an MEng in Design Engineering with First Class Honors from Imperial College London and attended Massachusetts Institute of Technology (MIT) from 2022 to 2023 as a Master of Business Analytics candidate, with work tied to MIT Sloan and the Operations Research Center.
He is also a member of the Association of Certified Anti-Money Laundering Specialists (ACAMS), a membership he began in 2025 that connects his technical work to the broader anti-money-laundering field.
His public activity in AI follows the same hands-on pattern. He has spoken at San Francisco's Fintech Summit and Imagination In Action, and given a TEDx talk on AI agents and human judgment.
Both the MCP Hackathon and RoboHacks at Y Combinator listed him as a judge in 2026. In 2024, the Élysée invited him to two separate occasions: a May assembly of French AI talent and a September preparatory meeting for the AI Action Summit.
Berkovic's philosophy positions machine intelligence as infrastructure around human judgment. It also shapes how technology reaches an institution.
Rather than treating implementation as a long software-engineering project, the Sphinx approach is described as a high-touch service with a comparatively light technical burden.
Berkovic describes the Interpretable Agentic Framework as a "multi-agent architecture purpose-built for regulatory-grade financial crime decisions."
He says it's not adapted from general-purpose large language models, but can integrate production machine learning systems into a client's existing technology stack "with essentially zero engineering effort on their side."
It is also a practical bridge: "We have careful abstraction of data access, tool use, and evaluation loops. It is why the system can move from pilot to production in days rather than months inside multiple U.S. institutions."
Ian Gilligan, who holds CAMS and CAMS-FCI credentials, led Axos Bank's 2025 review of sixteen AML AI vendors and later worked with Sphinx on the ground. Gilligan says: "He sat with my team and translated our written BSA/AML procedures into agent logic, line by line. He trained the staff himself."
Judgment Remains the Essential Product
Accountability is the design constraint. Sphinx organizes evidence and produces calibrated recommendations, but people still own the hard calls.
Berkovic says: "We treat machine learning not as a replacement for human judgment but as infrastructure that removes the friction preventing human judgment from being applied where it is most valuable."
He states the client message directly: "We are not here to replace their judgment. That judgment remains the essential product. We are here to remove the low-value friction so that human expertise can be reserved for the decisions that actually require it."
Analysts review edge cases and high-risk outcomes, especially when the evidence is thin or a mistake would carry real weight. Gilligan frames why that accountability matters in supervised banking: "The real barrier to AI in bank compliance is not whether a model can score an alert. It is whether the decision can be defended to a federal supervisor."
Jorgen Osio Norgaard, Chief Compliance and Risk Officer at Alviere and a Sphinx customer, saw the same hands-on pattern from the client side. Norgaard says: "He did the model work himself. He sat between my compliance function and the AI."
For institutions that need a stronger human presence, Sphinx also operates a managed service called Sphinx Frontline. It places both AI agents and human analysts inside client systems where institutions require human-in-the-loop oversight.
The arrangement makes the human layer part of the operating system, not an afterthought. Analyst feedback can inform controlled updates to agents, with changes evaluated rather than introduced invisibly.
The decision to preserve expert judgment while automating the evidence work around it is unusual in a market where AI products are often presented as replacements for manual compliance processes.
But it is making waves. Berkovic says the framework has also attracted professional attention: "What we have developed and documented has been examined and, in some cases, adapted internally by other organizations. We have also assisted companies that preferred to implement components of the approach themselves. Public discussion of the methods has reached a substantial professional audience; practitioners have incorporated aspects of the thinking into their own systems."
As a result, multi-agent decision processes are more intelligible in regulatory settings. At the same time, the credential-based integration model reduces the technical barrier to adoption: "That combination can matter as much as raw model performance," says Berkovic, "because institutions must be able to understand, operate, review, and govern the systems they put into production."
He goes on to point out the benefit to operations, citing tangible results: "Across our portfolio we have freed hundreds of analyst hours weekly," reveals Berkovic.
"This has led to sharply reduced false-positive rates, and improved the consistency of decisions that ultimately reach U.S. regulators and partner banks."
The multi-agent Interpretable Agentic Framework has also measurably reduced hallucination and error rates by about 94 percent compared with comparable single-model systems built on general-purpose large language models.
That improvement translates directly into fewer erroneous decisions, lower operational cost, and stronger regulatory posture for U.S. institutions.
These results stem from careful data science engineering. It includes feature design, model calibration, multi-agent orchestration, and continuous evaluation applied to regulated workflows.
However, according to Berkovic, the practical test is whether automation removes administrative burden without removing accountability: "I believe that when it does, AI can increase the amount of expert attention available to a compliance organization rather than simply increasing the number of cases processed by software," he says.
Financial crime and identity verification will only get harder as generative AI makes fraud, impersonation, document manipulation, and synthetic identities more accessible.
That will of course raise the value of automation, but it also raises the cost of allowing opaque systems to make consequential decisions without meaningful human review.
The long-term significance of Berkovic's approach is therefore at the infrastructure level: "You need to build systems that absorb repetitive evidence work while protecting the attention and responsibility of the people who must make difficult calls," he says.
Berkovic sees the goal as protecting human judgment from low-value friction so that expertise remains available where uncertainty and consequences are highest.
He states the motivation directly: "Building machine learning systems that solve a large-scale, consequential problem, financial crime and identity verification, in a way that protects institutions and individuals, especially within the United States. The work sits at the infrastructure layer of trust in an economy increasingly mediated by AI. Contributing to that layer while leading a team of strong data scientists and engineers is what sustains the intensity."
What matters is that the people responsible for compliance can actually do that job, while the machines clear away the busywork that currently gets in the way.
About The Author
Mahadharani Vijay is a writer specializing in Lifestyle, Electric and Concept Cars, Science and Technology, and Markets, with a focus on transforming emerging trends and innovations into clear, engaging, and accessible stories for professionals and broader audiences.
.webp)



Comments